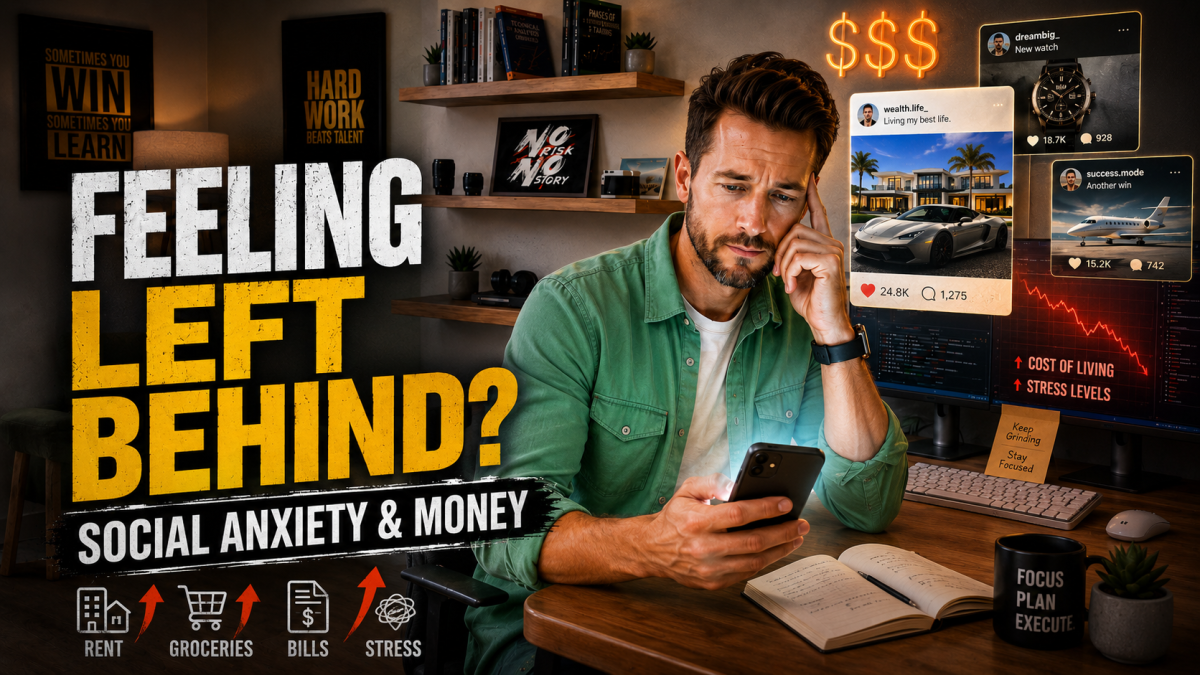
Do you ever get the feeling that everyone else is moving forward while you are somehow falling behind? You open Instagram and see a twenty-two-year-old standing next to a Lamborghini. Someone in Dubai explains how they became a millionaire through crypto, another person claims to work two hours a day from a laptop while earning more in a month than many people make in a year, and after a few minutes of scrolling it can start to feel as though extraordinary success has somehow become normal.
Then you put the phone down and return to ordinary life: work, housing, bills, groceries, transportation, and all the other expenses that continue arriving every month. That contrast can create an uncomfortable question: “What am I doing wrong?” More and more people seem to be experiencing some version of that pressure - not necessarily because their own lives are collapsing, but because the gap between ordinary life and the lives displayed online has become impossible to ignore.
In this article, “social anxiety” is not being used as a clinical diagnosis. It describes the broader economic and social unease that can appear when the world seems to be changing quickly, differences between people become more visible, and it becomes increasingly difficult to understand where your own path fits into everything around you.
Social media does not show you everyone else’s entire life. It shows you selected highlights - and then invites you to compare them with every ordinary hour of your own.
It Can Feel Like Two Completely Different Worlds Exist at the Same Time
In one world, someone works remotely from a laptop, has a flexible schedule, possesses a rare skill, owns a business, or has accumulated enough capital that some of their money works for them. They may work fewer hours than the average employee while earning substantially more.
In another world, someone works eight hours, spends another two commuting, takes a second job in the evening, works weekends, and still struggles to save anything meaningful. Both people may work extremely hard, yet the economic results can be completely different.
That is psychologically difficult because many people grew up with a much simpler model: work harder and you earn more. Hard work still matters, but in the modern economy there is no guarantee that the amount of physical or mental exhaustion created by one hour of work will determine how much that hour is worth.
Not Every Hour of Work Has the Same Economic Value
The market generally does not pay more because somebody had a harder day or finished twelve hours completely exhausted. Compensation tends to depend more on how much economic value can be created in a given period and how difficult the skill, system, or output is to replace.
One person may spend an hour moving boxes while another solves a software problem affecting thousands of users. One person serves ten customers personally, while another creates a digital product that can be used by ten thousand people. One person sells each hour individually, while another builds a system capable of generating value without requiring their direct presence every minute.
None of this means one person has more human value than another. It means the economic value assigned to different kinds of work can vary dramatically. If the real problem is that your income per hour is too low, adding three more hours to the day may help temporarily, but increasing the value of one hour can eventually become a more powerful long-term strategy.
The Job Market Is Changing at the Same Time
Automation, artificial intelligence, remote work, digital businesses, global hiring, and platform-based work are changing what employers need and what individuals can offer. Some tasks may gradually require fewer people, while specialized skills that can be delivered digitally may suddenly become valuable across an international market.
That makes the old model of learning one profession in your twenties and doing essentially the same job until retirement look less secure than it once did. One of the most important skills of the next few decades may not be a single profession at all. It may be the ability to learn, adapt, and rebuild your skill set repeatedly as technology and the labor market change.
More Possibilities Can Create More Anxiety
The traditional path was never guaranteed to be easy, but it at least appeared relatively clear: school, job, home, family, retirement. There was a map. Today, there are far more possible combinations.
You can be an employee, freelancer, entrepreneur, content creator, remote worker, investor, trader, programmer, consultant, or several of those things simultaneously. You can work for a local company, an international company, or clients scattered across several countries.
That freedom is valuable, but it has a psychological cost. When there are endless possibilities, it becomes easy to wonder whether the path you chose was the wrong one.
The Endless Opportunity Trap
Someone starts an e-commerce business and you wonder whether you should open an online store. Someone makes money in crypto and you wonder whether you missed the opportunity. Someone launches an AI company, buys property, starts a YouTube channel, or claims to live from Forex, and suddenly every new example becomes another possible life you could have chosen.
The danger is not necessarily having too few opportunities. It can be having so many that you constantly switch attention before any one path has enough time to produce meaningful results. You become interested in everything while building almost nothing deeply enough.
Social Media Makes the Comparison Almost Impossible to Win
Online, everybody appears wealthy, attractive, productive, and successful. Businesses are growing, trades close in profit, people work from Bali, and twenty-three-year-olds announce retirement. What rarely appears with the same intensity are failed businesses, debt, bad investments, unemployment, anxiety, uncertainty, and the periods when people had no idea what they were doing.
Social media is therefore less like life and more like a trailer for life. It usually presents the most interesting two minutes and leaves out most of the boring, painful, confusing, and unsuccessful parts. Comparing those selected highlights with your own complete twenty-four hours creates an unfair comparison before it even begins.
The “Millionaire in Your Twenties” Culture Distorts Expectations
There are genuinely extraordinary young entrepreneurs and investors, and their success does not need to be dismissed. The problem begins when rare outcomes are presented often enough that they start to look normal.
Twenty-two and no company? You are behind. Twenty-five and not a millionaire? Something must be wrong. Thirty and still working? Too late. Those expectations ignore reality.
People begin from different families, countries, health conditions, financial situations, opportunities, talents, networks, and levels of luck. Timing alone can create enormous differences. Someone achieving something at twenty-three does not mean somebody else is too late at thirty-five because life is not a single race with one shared stopwatch.
FOMO Becomes Dangerous When It Mixes With Financial Insecurity
Crypto and trading marketing can intensify this pressure with messages such as “ten minutes a day,” “passive income,” “secret strategy,” or “if you do not get in now, you will miss out.” Financial insecurity, social comparison, and FOMO are a particularly dangerous combination because they make risky decisions feel emotionally necessary.
When everyone around you appears to be getting rich, it becomes easier to put too much capital into one opportunity, use leverage you do not fully understand, chase speculative assets, or trust someone you would normally question immediately. The decision is no longer driven only by the quality of the investment. It is driven by a fear that your own life is moving too slowly.
Anxiety is a poor financial advisor. Trying to “catch up” through one trade, one coin, or one oversized bet can destroy the stability you were trying to build.
You Do Not Have to Catch Up With Anyone
You do not need to earn the same amount as somebody else at the same age, drive the same car, own the same house, build the same business, or have the same number of followers. Those comparisons create targets that may have very little to do with your own life.
A more useful comparison is with yourself one year ago. Do you understand more? Have more savings? Earn more? Carry less bad debt? Possess more valuable skills? Make better financial decisions? If the answer to several of those questions is yes, then you are moving forward even if somebody on TikTok happens to be sitting in a Bugatti.
Financial Stability Is Much Less Exciting Than Wealth
Stability rarely produces viral content. “I paid every bill on time again this month” is not going to attract a million views. Neither will “I have six months of emergency savings” or “I decided not to finance a car I could technically afford.”
But these quiet achievements can be extremely powerful. Financial stability is often boring, and boring can be good. It creates resilience rather than spectacle.
What Does Financial Stability Actually Mean?
It does not necessarily mean being rich. It means fewer events can destroy your financial life in one moment. If the car breaks down, it is inconvenient rather than catastrophic. If you lose your job for two months, you do not immediately need high-cost debt. If one expense rises, the entire budget does not collapse.
It also means that one bad investment does not wipe out everything you have built. That may not look as impressive as a luxury car on social media, but it can provide something arguably more valuable: better sleep.
Build a Floor Before You Build a Fortune
Before asking how to become a millionaire, it may be more useful to ask what would happen if your income disappeared for three months tomorrow. If the answer is complete financial disaster, then a speculative portfolio may not be the most important project yet.
The first priority may be building a floor: emergency savings, understanding your regular expenses, managing debt, developing marketable skills, and creating more secure or diversified sources of income. These things are not exciting, but they make later risk-taking much easier to approach calmly.
Before trying to maximize upside, reduce the number of ordinary events that could financially destroy you.
Do Not Think Only in Terms of Working More
When income is too low, the immediate reaction is often to work more. Sometimes that is necessary, especially temporarily, but there is a practical limit because every person has only twenty-four hours in a day.
Working ten, twelve, or fourteen hours indefinitely may eventually reach a ceiling where there are simply no more hours left to sell. That is why a second question matters: how can one hour of your time become more valuable?
The answer may involve new knowledge, specialization, technology, automation, a better job, a service, or a business. That path can take longer than simply adding another shift, but the long-term difference can be much greater.
Have Your Own Goals Instead of Instagram’s Goals
It is remarkably easy to adopt somebody else’s idea of success. A Ferrari becomes desirable because successful people display one. A Rolex becomes a goal because it appears repeatedly online. Five million dollars sounds like the required number even though you have never actually calculated why five million would be necessary.
A more useful question is what a good life means specifically to you. Maybe it means owning a home, being debt-free, earning $5,000 per month reliably, working four days a week, traveling for several months each year, operating a small business, retiring earlier, or simply reaching the end of the month without fear.
When the goal is genuinely yours, other people’s results become much less threatening because you are no longer competing inside a game you never deliberately chose.
Measure What You Can Control
You cannot control the stock market, the economy, interest rates, other people’s salaries, or the timing of the next recession. Trying to create certainty around those variables is likely to produce frustration because they are fundamentally outside your control.
You can influence how much time you spend learning, how much you save, how much risk you take, which skills you build, how many jobs you apply for, how many clients you contact, and which unnecessary expenses you reduce. Focusing on what can realistically change over the next six months creates a much healthier framework than trying to control the global economy.
Uncertainty Is Probably Not Going Away
It is tempting to postpone action until the economy becomes stable, the crisis ends, prices fall, housing becomes affordable, or the job market improves. But the world continually produces new sources of uncertainty: inflation, war, recession fears, AI disruption, political conflict, bubbles, housing costs, and interest-rate changes.
Perfect peace of mind may never arrive from the outside. Instead of waiting for the world to become stable, the more realistic objective may be to build as much stability around yourself as possible.
Resilience Is More Realistic Than Perfect Prediction
You cannot prevent a company from announcing layoffs, but savings and useful skills can reduce the damage if it happens. You cannot know what the stock market will do next year, but you can control the amount of capital you expose to risk.
You cannot determine future inflation, but you can try to increase your income and improve your financial flexibility. You cannot control the economy, but you can become more resilient to it. That is a much more realistic goal than trying to predict the future perfectly.
Feeling Worried Does Not Mean You Have Failed
It is understandable to feel uncertain about money, housing costs, employment, technological change, or what your career might look like five years from now. Looking at salaries, asset prices, and social media at the same time can easily create the feeling that keeping up is becoming impossible.
The real danger is not experiencing worry. The danger is allowing it either to paralyze you completely or to push you into trying everything at once. Doing nothing out of fear and taking reckless action out of panic can both produce poor outcomes.
Turn Worry Into a Plan
If you are worried about losing your job, turn that fear into concrete preparation: build emergency savings, update your résumé, develop another skill, strengthen professional relationships, and look at alternative opportunities before they become urgently necessary.
If money feels insufficient, examine expenses, income opportunities, learning, and saving. If you are afraid of missing an investment opportunity, do not buy simply because of FOMO. Learn what you are buying, why you are buying it, how much risk you are taking, and how long you expect to hold it.
Anxiety says, “Something bad is going to happen.” A plan says, “If something bad happens, this is what I will do.” Psychologically and financially, that is a major difference.
More Money Does Not Automatically End Comparison
Money can solve many practical problems, but it does not automatically solve the tendency to compare. Someone with one million dollars can compare themselves with somebody who has ten million. Someone with ten can look at somebody with one hundred. No matter how high the number becomes, there will almost always be somebody richer, younger, more successful, more attractive, or more popular.
That is a game you cannot permanently win. If the goal is to relax only when nobody has more than you, relaxation never arrives.
Define What “Enough” Means for You
Having a definition of enough does not mean abandoning ambition or refusing to grow. It means identifying a point where you know that your basic financial security has become strong enough to reduce unnecessary fear.
Enough might mean six to twelve months of savings, eliminating bad debt, reaching a certain monthly income, owning a home, operating a stable business, or building a clearly defined investment portfolio. These are specific goals that can be measured.
“I want to be richer than the internet” is not a measurable goal, and it is unlikely to create peace because the internet can always find somebody wealthier.
Your Definition of Success Can Change
At twenty-five, success might look like a sports car. At thirty-five, it may look like a quiet home. At forty-five, it may become more free time, and at fifty-five, security may matter more than status.
That change is normal. You are allowed to revise your definition of success as your life changes. Wanting something once does not obligate you to remain the same person forever.
Where SignalCrumbs Fits Into This
If part of your financial uncertainty comes from not understanding markets or wanting to learn more about Forex and automated trading, that is one area where knowledge can be improved. At SignalCrumbs, we share a closer look at the activity and thinking behind our own automated trading system together with educational material about Forex, margin, leverage, risk, and systematic trading logic.
But no trading platform or educational website can eliminate economic uncertainty or build financial stability on somebody’s behalf. It can be a learning tool or a starting point, but stability is a much larger project involving savings, income, risk management, self-discipline, knowledge, and realistic goals.
Realistic Goals Build More Than Flashy Targets
“I must be a billionaire by thirty” may sound ambitious, but goals such as building three months of emergency savings within a year, earning 20% more within two years, learning a marketable skill within six months, saving every month, or refusing to risk an entire savings balance on one opportunity are much more actionable.
They may not produce impressive social-media content, but they can build a life. Slow, repeatable improvements can create stability long before they create anything that looks spectacular from the outside.
Final Thoughts
The world is genuinely uncertain. Work is changing, living costs can rise quickly, technology is creating new winners and losers, and some people are benefiting enormously while others work harder just to maintain the same standard of living. At the same time, social media constantly presents selected examples of people who appear wealthier, younger, freer, and more successful.
It is important to separate two things: uncertainty in the world and your level of preparation. You cannot eliminate the first. You can work on the second by building savings, improving your skills, learning how money and markets work, controlling risk, and avoiding the urge to catch up with everybody else through one trade, one cryptocurrency, or one business idea.
Build more slowly if necessary. Build more boringly. But build more steadily, and define success in a way that actually belongs to you. Maybe success is not sitting in a Lamborghini at twenty-five. Maybe it is reaching forty without being terrified that losing two months of income would destroy everything you have built.
Perhaps it is not one million followers either. Perhaps it is having a life you do not constantly want to escape from.
If financial markets and Forex are among the areas where you want to build stronger knowledge, you can find educational material and a closer look at how our own automated trading system works at SignalCrumbs.com .
The goal is probably not to eliminate every uncertainty from life. It is to build something stable around yourself even while the world remains uncertain - and you do not have to become a millionaire tomorrow to start doing that.
 Related posts